


Can the Lender Change the Interest Rate on My Personal Loan?

- Personal loans normally have fixed interest rates that don’t change.
- If you want to get a lower interest rate, you can try to refinance your personal loan.
- The interest rate is different from (and sometimes lower than) the APR, which represents the total cost of the loan, including interest and fees.
Free up cash each month with Freedom Debt Relief
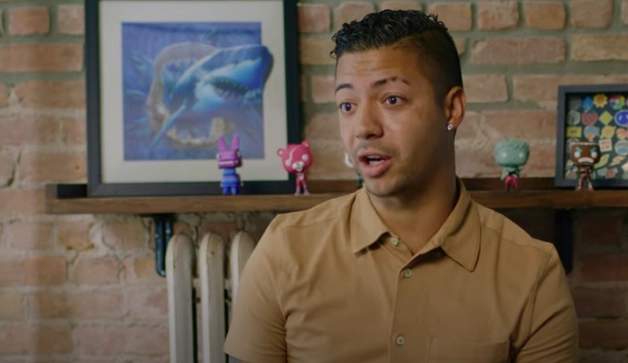
Ozzy S., Freedom client²
“Right away, I had more money each month because of program costs so much less than what I was paying on my minimums.”


Reasonable interest rates are one of the main benefits that personal loans offer. On average, personal loan rates are about 10% lower than credit card rates, according to the Federal Reserve. That’s a sizable difference, and it’s why using a personal loan for debt consolidation is often a smart move. You could save quite a bit on interest, especially when you consolidate credit card debt.
If you have a personal loan, or you’re thinking about getting one, you may be wondering if the interest rate is guaranteed as long as the loan lasts. This is a good question to ask so you know exactly what to expect from your loan.
Can the Lender Change the Interest Rate on My Personal Loan?
A lender normally can’t change the interest rate on a personal loan during the loan term. Most personal loans have fixed interest rates. A fixed rate stays the same for the life of the loan, so there are no surprises. From the start, you know your loan’s interest rate, monthly payment amount, and how long it will take to pay back.
To find out if your loan has a fixed rate, check your loan agreement. If you haven’t applied for a loan yet, you can usually find out if a lender offers fixed-rate loans by checking its website. You can also contact the lender directly to ask if its personal loans have fixed interest rates.
There are a couple of situations where your interest rate on a personal loan could change: if you have a variable-rate loan or if you refinance.
Variable-rate loans
A variable rate is an interest rate that can go up or down over time. Variable interest rates are usually tied to a benchmark rate. For example, a variable rate could be connected to the federal funds rate, which is an interest rate set by the Federal Reserve.
The lender can make rate changes with this type of loan, but it can’t just change the variable rate to whatever it wants. It makes rate changes based on movement in the benchmark rate.
When it comes to personal loans, fixed rates are the norm. Variable rates are more common with other types of financial products. Almost all credit cards have variable rates, and so do some mortgages—these are called adjustable-rate mortgages.
Personal loan refinancing
Refinancing a personal loan changes the interest rate you pay. When you refinance, you get a new personal loan to pay off the old one. The most common reason to refinance debt is to get a better deal, such as a lower interest rate or a cheaper monthly payment.
It’s not entirely accurate to say that your personal loan’s interest rate changes after refinancing. You’re replacing your original personal loan, and your new loan has its own interest rate. But that’s more of a technical detail. You’ll be paying a different interest rate, and most likely a lower one. It rarely makes sense to refinance and pay more.
Why Is My Personal Loan’s Interest Rate Different From the APR?
The annual percentage rate (APR) on a loan can be a little confusing. You might notice that your personal loan has an interest rate but also an APR, which is higher. The lender hasn’t changed anything, as these are two different types of rates. Here’s the difference:
The interest rate is the percentage charged every year for interest.
The APR is the total annual cost of the loan, including interest and any other fees the lender charges.
For example, some lenders charge an origination fee when you take out a personal loan. Origination fees depend on the lender, with 1% to 10% of the loan being the usual range. If your personal loan has an origination fee, the APR will include this fee. The interest rate won’t.
Imagine you get a $10,000 personal loan for five years. Your loan has a 10% interest rate and a 5% origination fee ($500). Because of that origination fee, the cost of your loan for a year would be about 12%, or 2% higher than just the interest rate.
How to Get Rid of Expensive Debt
If you’re having trouble keeping up with debt payments, debt consolidation is one potential solution. You could see if you qualify for a personal loan with a lower interest rate than your current debt. This can help when the debt is still manageable.
However, debt consolidation doesn’t work for everyone. People with low credit scores or large amounts of debt could struggle to qualify for a personal loan. And if your debt is far too expensive to fit your budget, consolidating it might not be enough.
In this situation, consider working with a debt relief program. A professional debt settlement company can negotiate with creditors and debt collectors on your behalf. Instead of juggling payments, you could make one affordable monthly deposit until you have a debt settlement agreement. After you finish the debt relief program, you can build a better financial future without costly debt holding you back.
Debt relief by the numbers
We looked at a sample of data from Freedom Debt Relief of people seeking credit card debt relief during September 2026.
Credit Card Usage by Age Group
No matter your age, navigating debt can be daunting. These insights into the credit profiles of debt relief seekers shed light on common financial struggles and paths to recovery.
Here's a snapshot of credit behaviors for September 2026 by age groups among debt relief seekers:
| Age group | Number of open credit cards | Average (total) Balance | Average monthly payment |
|---|---|---|---|
| 18-25 | 3 | $7,868 | $252 |
| 26-35 | 5 | $11,313 | $347 |
| 35-50 | 6 | $15,373 | $431 |
| 51-65 | 8 | $16,698 | $516 |
| Over 65 | 8 | $17,060 | $473 |
| All | 7 | $15,142 | $424 |
Whether you're starting your financial journey or planning for retirement, these insights can empower you to make informed decisions and work towards a more secure financial future
Collection accounts balances – average debt by selected states
Collection debt is one example of consumers struggling to pay their bills. In September 2026, 30% of debt relief seekers had a collection balance. The average amount of open collection account debt was $3,203. Here is a quick look at the top five states by average collection debt balance:
Collection accounts - top 5 states
| State | % with collection balance | Avg. collection balance |
|---|---|---|
| District of Columbia | 23 | $4,899 |
| Montana | 24 | $4,481 |
| Kansas | 32 | $4,468 |
| Nevada | 32 | $4,328 |
| Idaho | 27 | $4,305 |
The statistics are based on all debt relief seekers with a collection account balance over $0.
If you’re facing similar challenges, remember you’re not alone. Seeking help is a good first step to managing your debt.
Tackle Financial Challenges
Don’t let debt overwhelm you. Learn more about debt relief options. They can help you tackle your financial challenges. This is true whether you have high credit card balances or many tradelines. Start your path to recovery with the first step.
Show source
Author Information
Written by
Lyle Daly
Lyle is a financial writer for Freedom Debt Relief. He also covers investing research and analysis for The Motley Fool and has contributed to Evergreen Wealth and Monarch Money.
Reviewed by
Kimberly Rotter
Kimberly Rotter is a financial counselor and consumer credit expert who helps people with average or low incomes discover how to create wealth and opportunities. She’s a veteran writer and editor who has spent more than 30 years creating thousands of hours of educational content in every possible format.
Frequently Asked Questions
Can my lender increase my personal loan rate if I miss a payment?
Your lender probably can’t increase your personal loan rate if you miss a payment. Many cards have a penalty APR, but the same isn’t true with personal loans. While the lender may charge you a late fee, your loan’s interest rate should stay the same. To be sure, review your loan agreement to see if it says anything about rate increases.
What’s the difference between a fixed and a variable interest rate on a loan?
A fixed interest rate remains the same for the duration of the loan. A variable interest rate can change based on the movement of a benchmark rate.
Can I negotiate a lower interest rate on my personal loan?
You may be able to negotiate a lower interest rate on your personal loan. Lenders will sometimes work with you, especially if you’re going through a financial hardship. If not, another way to get a lower interest rate is to refinance your personal loan.